Exempt vs taxable
Healthcare services exempt under entry 74; medicines at 5% / 12%; devices at 5% / 12% / 18%. Per-service classification.

Exempt healthcare services, taxable diagnostics, GST on medicines, NPPA price ceilings, distributor reconciliation and multi-entity pharma chains. Built for mixed-supply complexity.
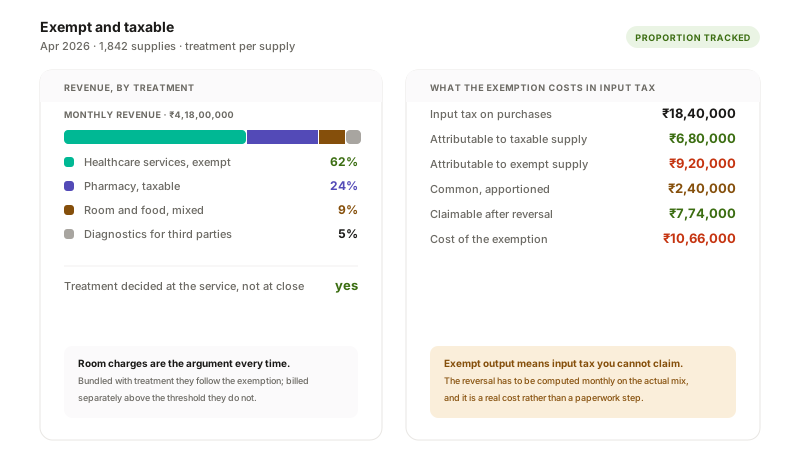
Healthcare services are largely exempt; medicines and devices are taxable; diagnostics sometimes both. The boundary is where the audit notice comes from.
Healthcare services exempt under entry 74; medicines at 5% / 12%; devices at 5% / 12% / 18%. Per-service classification.
In-patient bundled bills with mixed exempt/taxable lines. Out-patient with diagnostics and pharmacy splits.
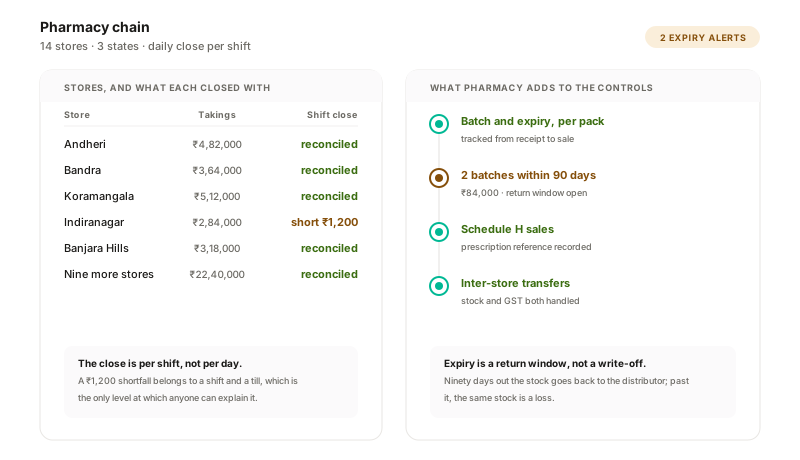
Multi-store, multi-state pharmacy chains. Per-store stock, per-state GSTIN, daily reconciliation.
NPPA price ceilings tracked per scheduled drug. Margin controls applied at sale.
Pharma distributors, C&F agents, super-stockists with per-distributor GSTIN, TDS, settlement reconciliation.
Medical equipment leasing with operating vs finance lease accounting per Ind AS 116.
A hospital bill has consultation (exempt), surgery (exempt), implant (taxable), diagnostics (mixed), pharmacy (taxable), room rent (taxable above ₹5,000/day under specific rules). OneFinOps applies the right tax to each line, generates the right GST split on a single patient invoice, and reports cleanly on the GSTR-1.
A pharmacy chain spread across 5 states and 50 stores has 5 GSTINs, 50 daily reconciliations, NPPA price tracking on hundreds of SKUs and a pharmacy stock that moves between stores. OneFinOps gives each store a workspace, each state its own GSTR-1/3B, and the chain a rollup.
Per Entry 74 of GST exemption notification 12/2017, healthcare services by a clinical establishment, authorised medical practitioner or paramedics are exempt. Diagnostics under prescription are exempt. Sale of medicines is taxable (5% / 12%). Implants supplied during surgery are typically composite supply with the surgery (exempt). Room rent above ₹5,000/day is taxable from 18 July 2022. OneFinOps applies the right rule per service line.
Hospitals making both exempt (services) and taxable (pharmacy, devices) supplies must reverse ITC on common inputs proportionate to exempt revenue under Rule 42/43 of CGST Rules. OneFinOps computes the monthly Rule 42 reversal, posts it to the GSTR-3B, and tracks the annual Rule 43 reversal at year-end.
Drug Price Control Order 2013 caps prices on scheduled drugs (NLEM). NPPA notifies ceiling prices monthly. OneFinOps tracks the ceiling per SKU per month, validates sale prices against the ceiling, and flags overruns before posting. Required for pharma manufacturers, distributors and chain pharmacies.
Pharma distributors deal with hundreds of SKUs, super-stockists, sub-stockists and C&F agents. OneFinOps handles distributor onboarding (GSTIN, drug licence validation), TDS at 194C / 194H per relationship, settlement reconciliation against distributor settlement reports and the per-distributor outstanding ledger.
A pharma group might be: a manufacturing entity, a marketing entity, a distribution arm, a contract manufacturing arm. Each is its own entity with its own books, GSTIN and statutory calendar. The group view consolidates with intercompany eliminations on inter-entity sales.
Operating lease (most equipment) is expense-as-incurred. Finance lease (rare, but happens for high-value imaging) is capitalised under Ind AS 116. OneFinOps applies the lease classification and posts the right journal entries.
A 30-minute walkthrough on your hospital, pharma or pharmacy operations.