GSTR-2B vs GSTR-3B reconciliation is the monthly check that the input tax credit you claim in Table 4 of GSTR-3B agrees with GSTR-2B, with every difference explained by a reversal, an ineligible credit or a timing item. Claim too much and a DRC-01C intimation arrives; left unanswered, it can block your next GSTR-1.
OneFinOps matches every GSTR-2B line to the purchase invoice before you file, so you only look at lines needing a decision.
Key takeaways
- Take full GSTR-2B credit into Table 4A, then reverse in Table 4B.
- Differences are normal when explained: blocked credit, 180-day reversals, re-claims.
- Table 3 of GSTR-3B is locked to GSTR-1; Table 4 ITC is editable.
GSTR-2B vs GSTR-3B: what is the difference?
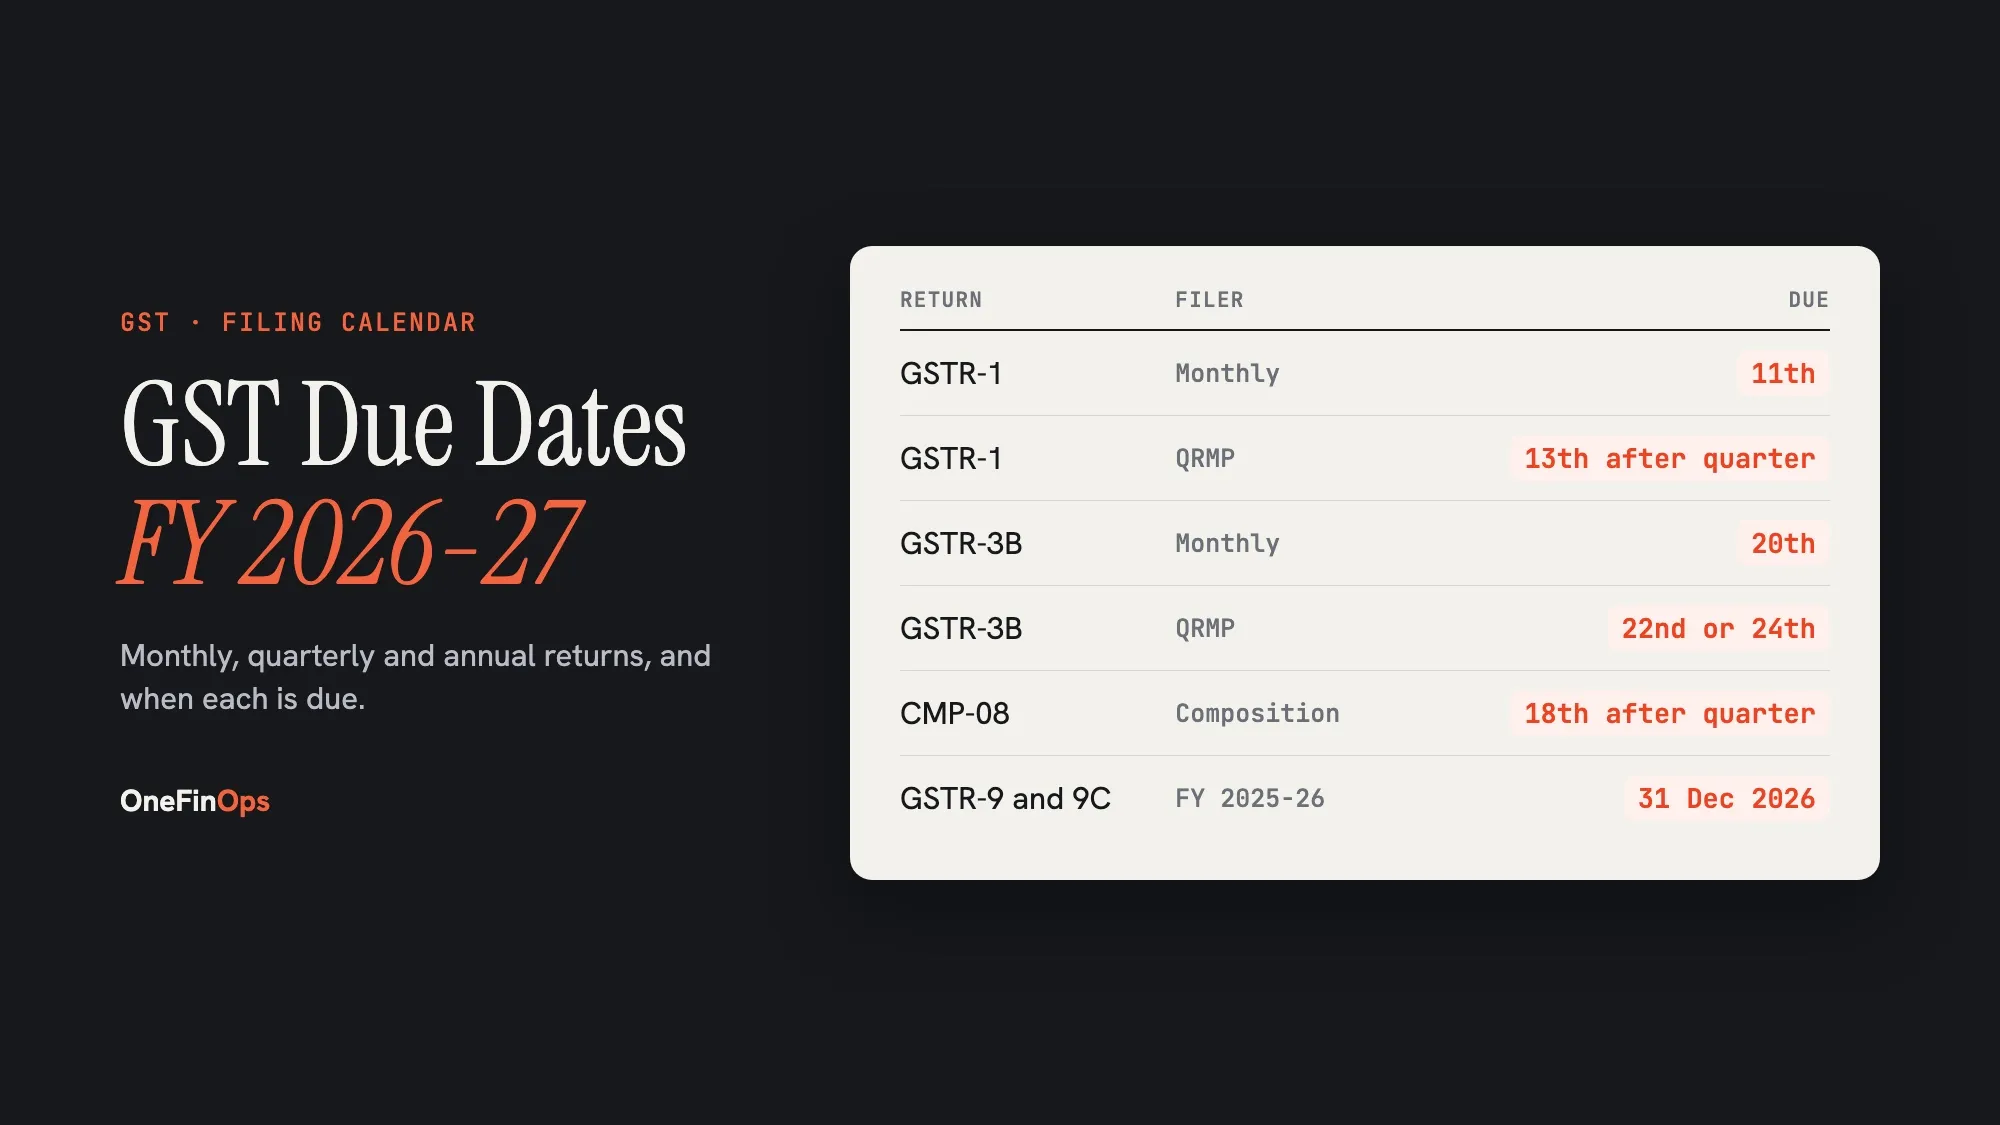
GSTR-2B is the auto-drafted ITC statement the portal builds on the 14th of the following month from suppliers’ filings and customs data. You change it only through IMS accept, reject or pending, and it is the basis for ITC under rule 36(4). GSTR-3B is the summary return you file by the 20th (22nd or 24th after the quarter for QRMP), where ITC is availed and tax paid. It cannot be revised. GSTR-2A keeps changing as suppliers amend; use it to investigate, not to decide the claim.
How GSTR-2B flows into Table 4 of GSTR-3B
Circular 170/02/2022-GST sets how each line is used.
| GSTR-3B table | What goes in |
|---|---|
| 4A(1) Import of goods | IGST on Bills of Entry, from GSTR-2B |
| 4A(3) Reverse charge | RCM tax paid in cash, partly self-assessed |
| 4A(5) All other ITC | Regular B2B invoices, net of credit notes, from GSTR-2B |
| 4B(1) Permanent reversal | Section 17(5), rules 38, 42 and 43 |
| 4B(2) Temporary reversal | Rule 37 (180 days), goods not received |
| 4D(1) ITC reclaimed | Earlier 4B(2) reversals now reclaimed |
| 4D(2) Ineligible ITC | Barred by section 16(4) or place of supply rules |
Example. Kaveri Components has ₹14,60,000 in GSTR-2B, plus ₹36,000 RCM and a ₹54,000 re-claim, so Table 4A is ₹15,50,000. It reverses ₹50,500 in 4B(1) and ₹71,000 in 4B(2). Net ITC in 4C is ₹14,28,500, ₹31,500 below GSTR-2B, all explained.
What happens if the numbers do not match?
- GSTR-3B cannot be revised. Corrections go in the next month’s return, within the section 16(4) time limit.
- Excess ITC wrongly availed and utilised attracts 18% interest under section 50(3).
- A DRC-01C gives you seven days to pay through DRC-03 or explain. Until then, rule 59(6) can block your next GSTR-1.
The conditions behind each line are in input tax credit in GST.
How OneFinOps handles GSTR-2B vs GSTR-3B
The Tax Agent reconciles the purchase register to GSTR-2B line by line, holding not reported, amount differs and matched as separate outcomes. It prepares GSTR-3B from the period’s postings and lists each difference with its cause.
People keep the decisions. The named preparer and reviewer see the return before submission, and credit at risk from a vendor who has not filed goes to the payables controller while the payment can still be held. When purchases, payments and returns sit in separate tools, that vendor is found after being paid; here the credit and the payment are on the same bill.