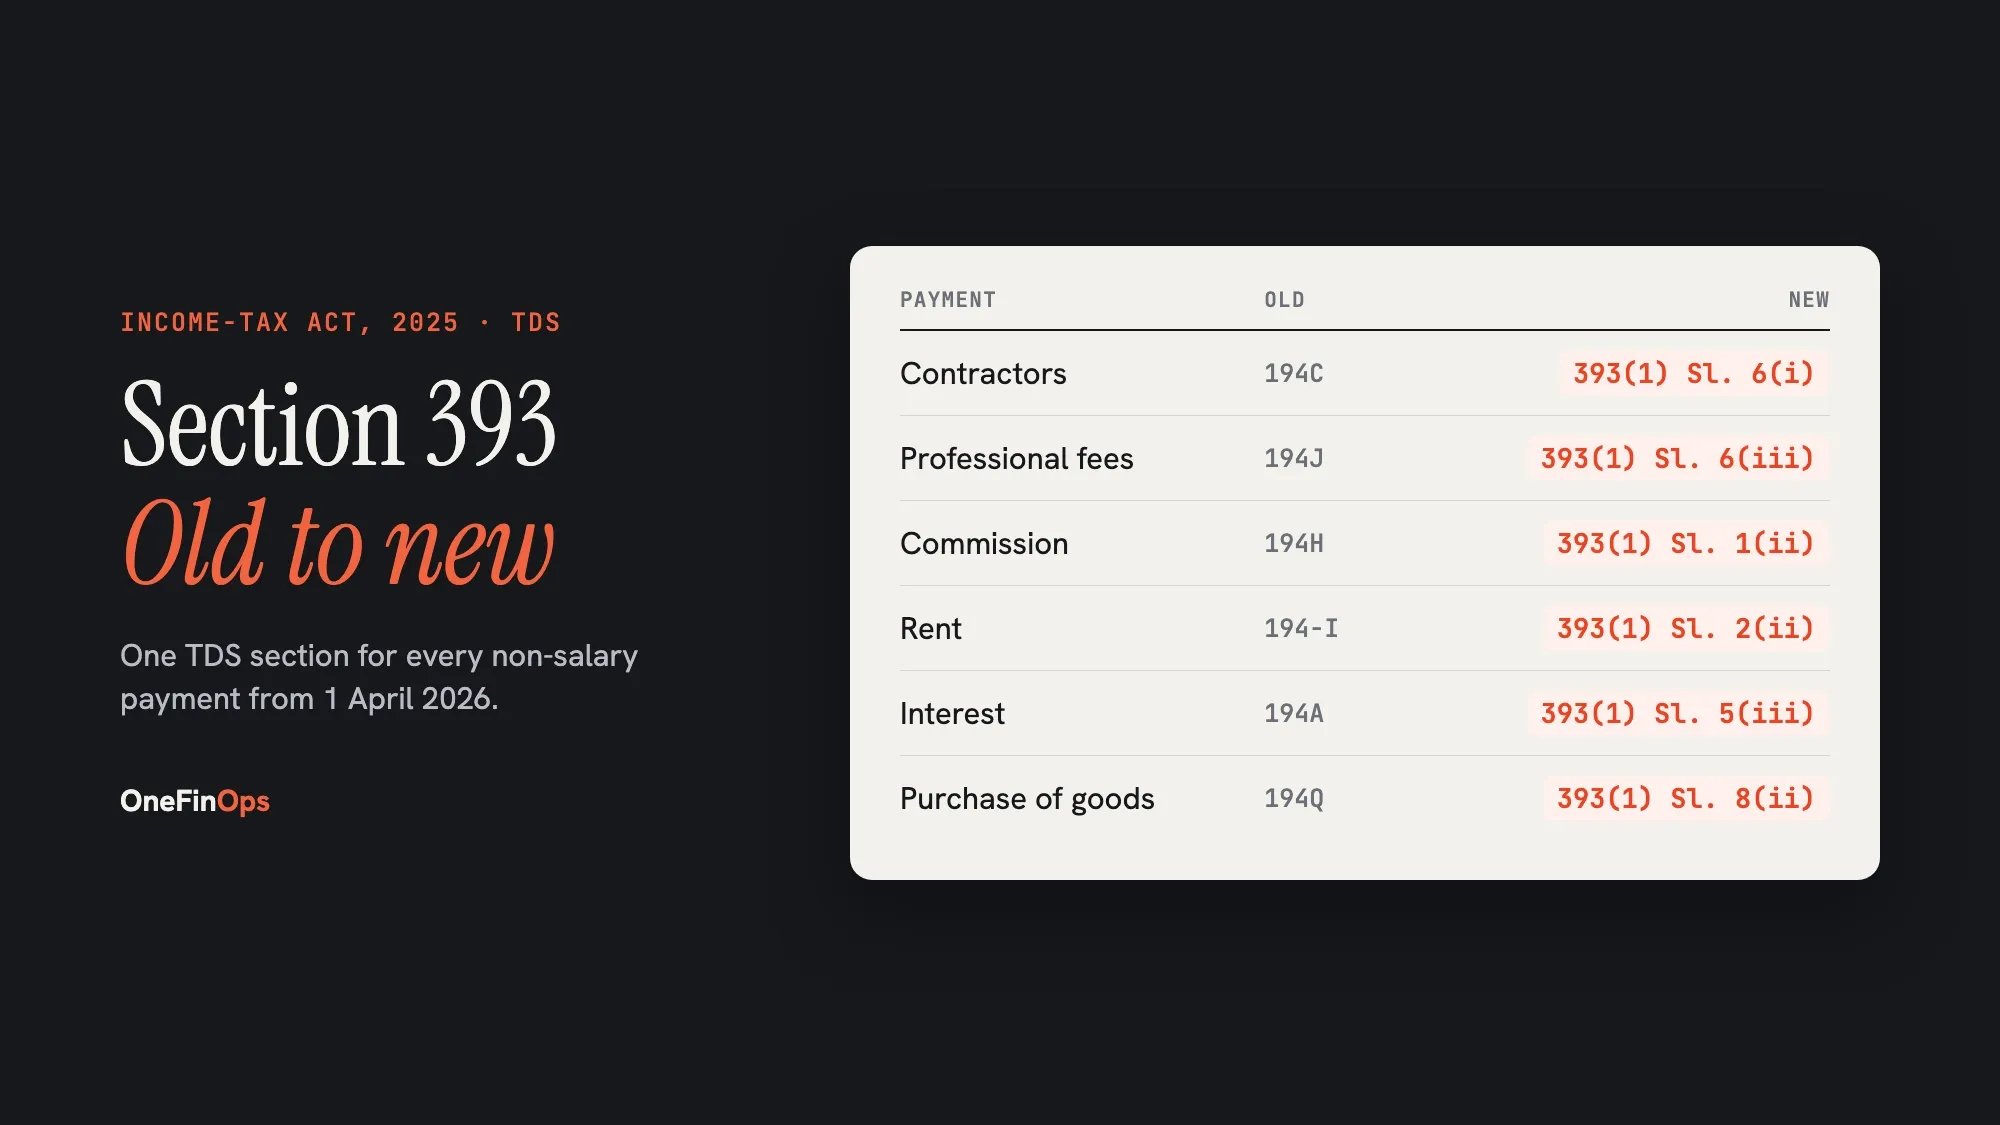
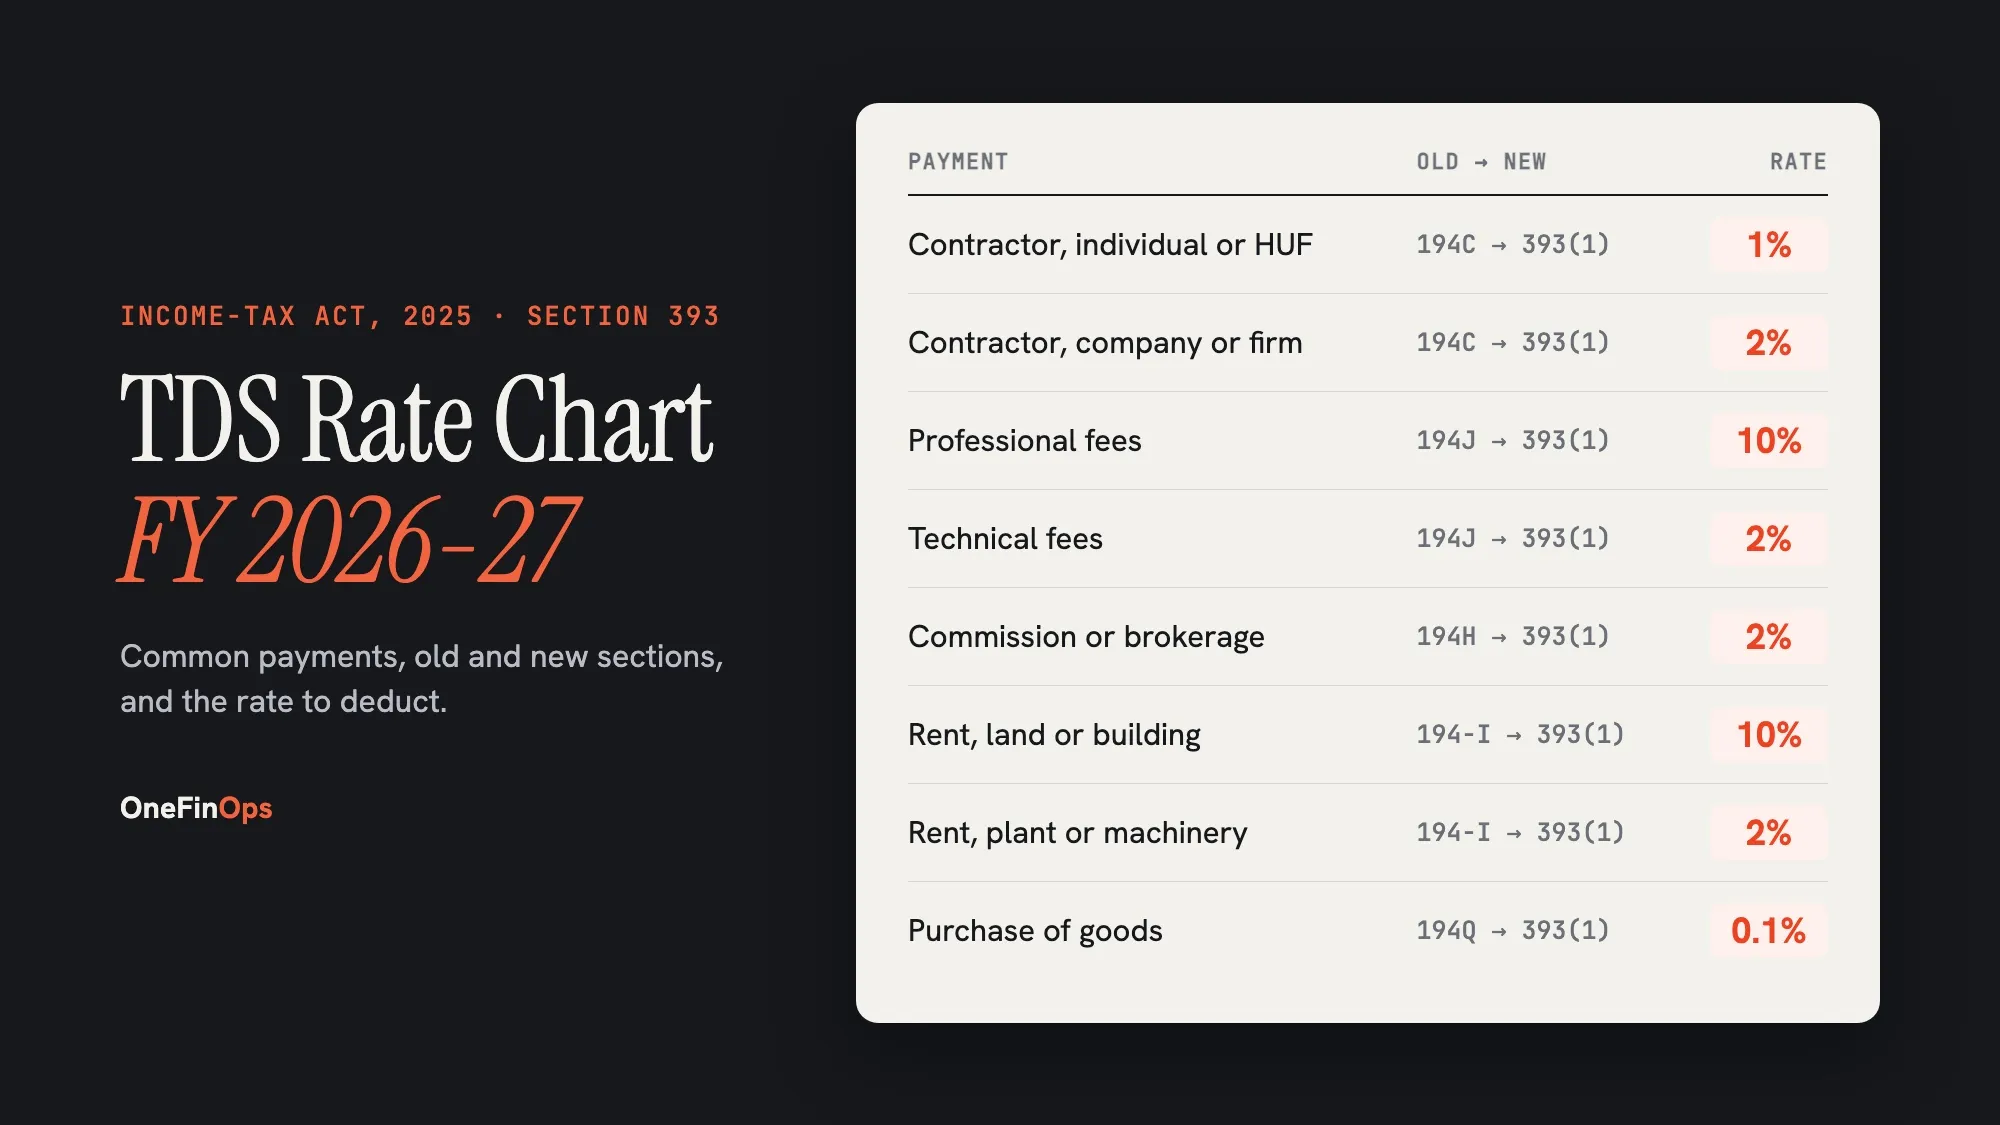
The TDS rate chart for FY 2026-27 lists the rate, threshold and section for each payment under the Income Tax Act 2025, in force from 1 April 2026. Sections and payment codes changed; most rates did not. One wrong row on a recurring vendor means short deduction every month, with interest running until someone notices.
To find one rate by old section or new payment code and calculate the TDS, use the TDS rate chart tool.
In OneFinOps, the rate and threshold are applied on each bill from the vendor’s status, not from memory.
Key takeaways
- Contractors 1% or 2%, professional fees 10%, rent 2% or 10%, goods 0.1%.
- Challans and returns use four-digit payment codes instead of section numbers.
- No valid PAN means at least 20% TDS (5% for goods and e-commerce).
TDS rate chart FY 2026-27: most used business payments
The rows an accounts payable team uses every week, for payments to residents.
| Nature of payment | Old section | New section | Payment code | Threshold (per payee, per tax year unless stated) | TDS rate |
|---|---|---|---|---|---|
| Contractor: individual or HUF | 194C | 393(1) Sl. 6(i) | 1023 | ₹30,000 single sum or ₹1,00,000 aggregate | 1% |
| Contractor: company, firm, LLP, others | 194C | 393(1) Sl. 6(i) | 1024 | ₹30,000 single sum or ₹1,00,000 aggregate | 2% |
| Fees for professional services | 194J | 393(1) Sl. 6(iii) | 1027 | ₹50,000 | 10% |
| Fees for technical services, film royalty, call centre | 194J | 393(1) Sl. 6(iii) | 1026 | ₹50,000 | 2% |
| Royalty (other than film) and non-compete fees | 194J | 393(1) Sl. 6(iii) | 1027 | ₹50,000 | 10% |
| Director fees or commission (not salary) | 194J | 393(1) Sl. 6(iii) | 1028 | Nil | 10% |
| Commission or brokerage | 194H | 393(1) Sl. 1(ii) | 1006 | ₹20,000 | 2% |
| Rent: land, building, furniture, fittings | 194-I(b) | 393(1) Sl. 2(ii) | 1009 | ₹50,000 for a month or part of a month | 10% |
| Rent: plant, machinery, equipment | 194-I(a) | 393(1) Sl. 2(ii) | 1008 | ₹50,000 for a month or part of a month | 2% |
| Purchase of goods (buyer turnover above ₹10 crore) | 194Q | 393(1) Sl. 8(ii) | 1031 | On the amount above ₹50 lakh per seller | 0.1% |
| Business perquisite or benefit | 194R | 393(1) Sl. 8(iv) | 1033 | ₹20,000 | 10% |
| Interest by a company, firm or other specified person | 194A | 393(1) Sl. 5(iii) | 1022 | ₹10,000 | 10% |
| Dividend by a domestic company | 194 | 393(1) Sl. 7 | 1029 | ₹10,000 for individuals paid other than in cash | 10% |
| Salary, remuneration, commission, bonus or interest to a partner | 194T | 393(3) Sl. 7 | 1067 | ₹20,000 | 10% |
| E-commerce operator to seller | 194-O | 393(1) Sl. 8(v) | 1035 | Nil (exempt for individual or HUF sellers up to ₹5 lakh with PAN or Aadhaar) | 0.1% |
Commission, rent, interest and professional fees apply only when the payer is a “specified person” (section 393 guide). Bank and post office interest is 10% above ₹50,000 (₹1,00,000 for senior citizens), and winnings are at 30%.
TDS rate when PAN is not available
Old section 206AA is now section 397(2)(b). Without a valid PAN, deduct at the highest of the row rate, the rate in force, or 20% (5% for goods and e-commerce). Section 206AB for non-filers has no successor.
Example: Nair Logistics Pvt Ltd receives an ₹80,000 software support invoice from a company that has not given its PAN. TDS rises from 2% (₹1,600) to 20% (₹16,000), due by 7 September 2026 for an August invoice (due dates).
How OneFinOps applies the TDS rate chart
In OneFinOps, the Payables Agent codes every incoming bill to its tax treatment. The section, rate and threshold are determined by the vendor’s status, and lower deduction certificates and exemptions are applied without anyone looking them up. The Tax Agent prepares the quarterly statement, reconciled to the ledger, but does not file on its own: the named preparer and reviewer see it first.
Most setups keep the bill in the books and the return in a separate TDS tool. Here they live on one record.