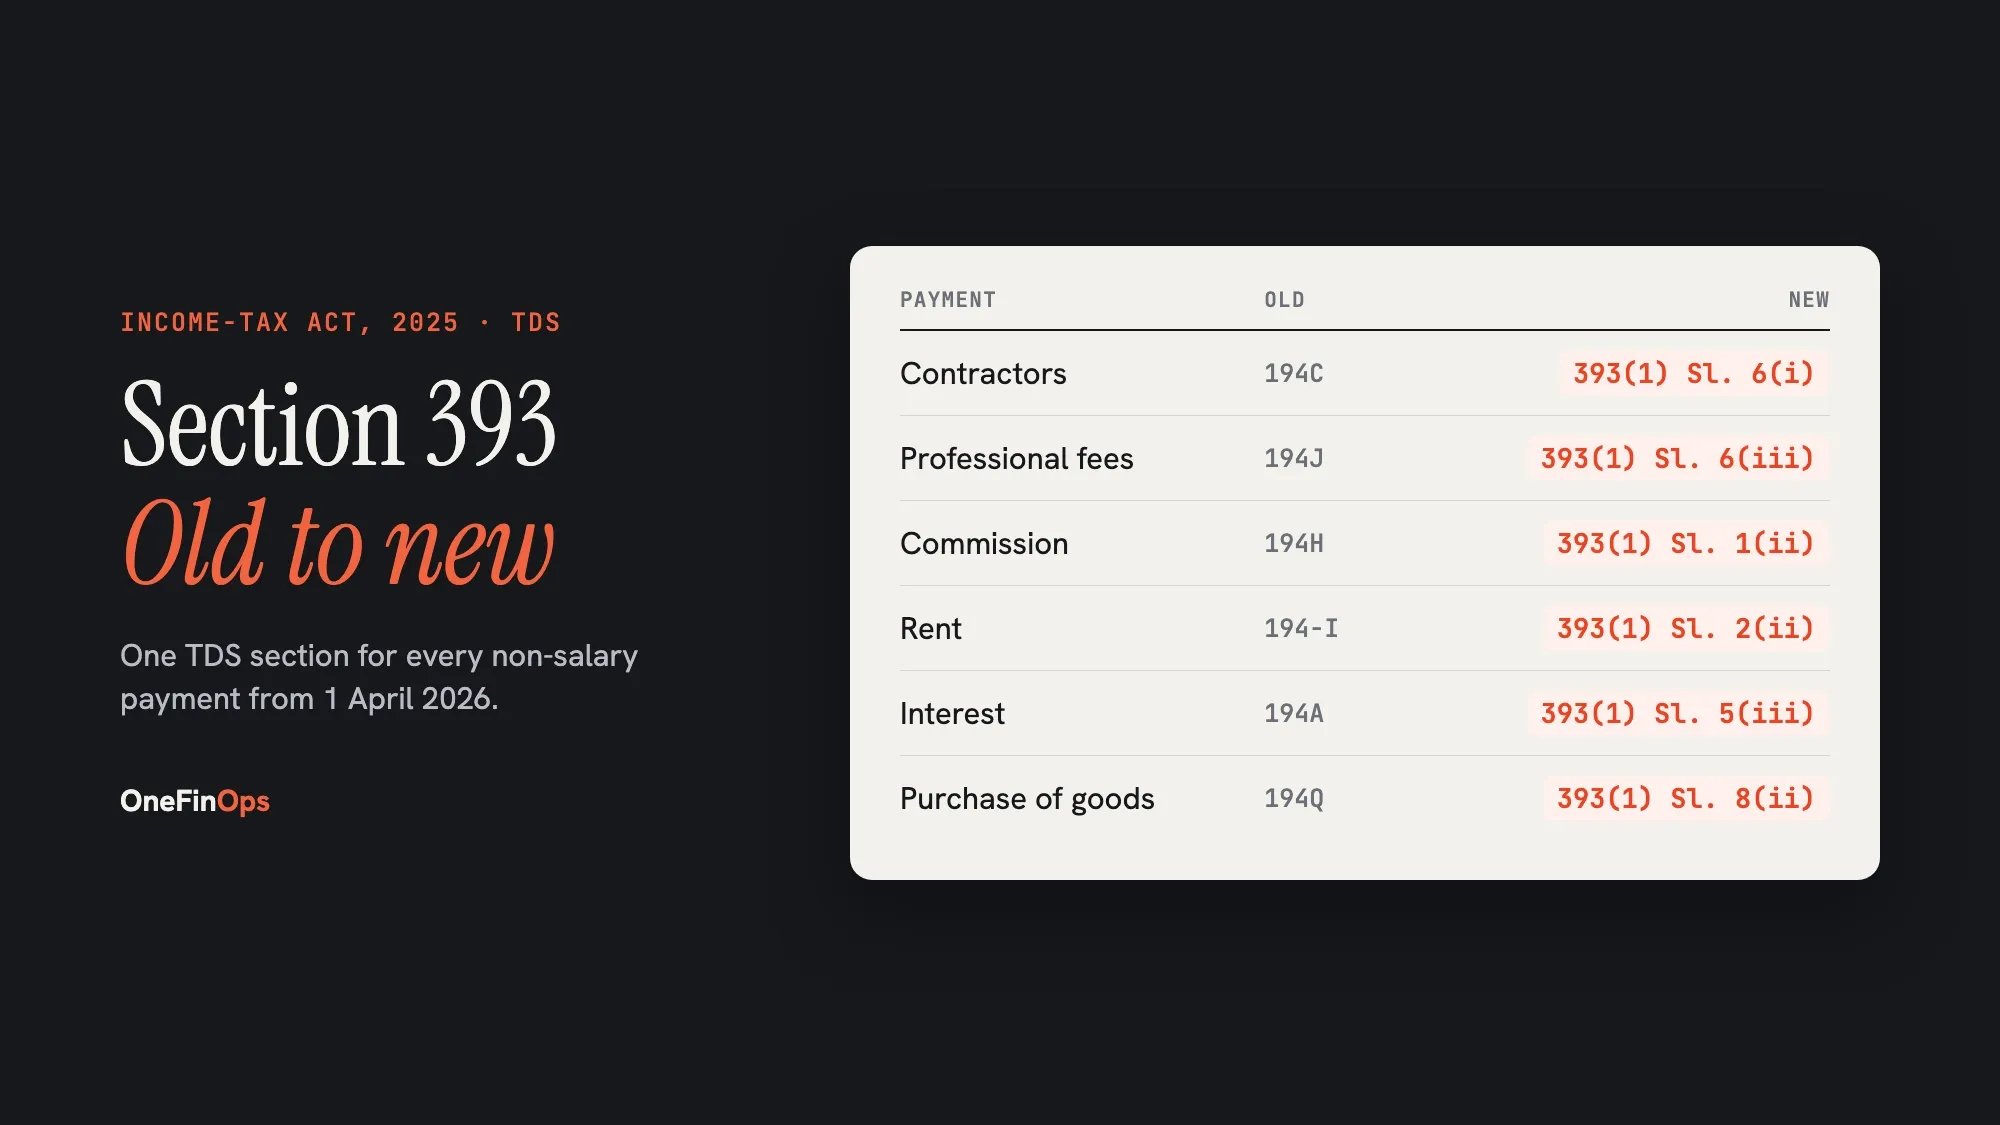
Section 393 of the Income Tax Act 2025 is the single TDS provision for every non-salary payment from 1 April 2026, replacing sections 193, 194 to 194T and 195. Rates barely moved, but every challan and return needs the right row and payment code. Pick wrong and the deposit, return and vendor’s credit are all wrong.
In OneFinOps, the section, rate and threshold are set on each bill from the vendor’s status, so the row is chosen once.
Key takeaways
- 393(1) covers residents, 393(2) non-residents, 393(3) any person.
- Rates and thresholds carried over; sections, forms and payment codes changed.
- Credit or payment on or after 1 April 2026 falls under section 393.
What is section 393 of the Income Tax Act 2025?
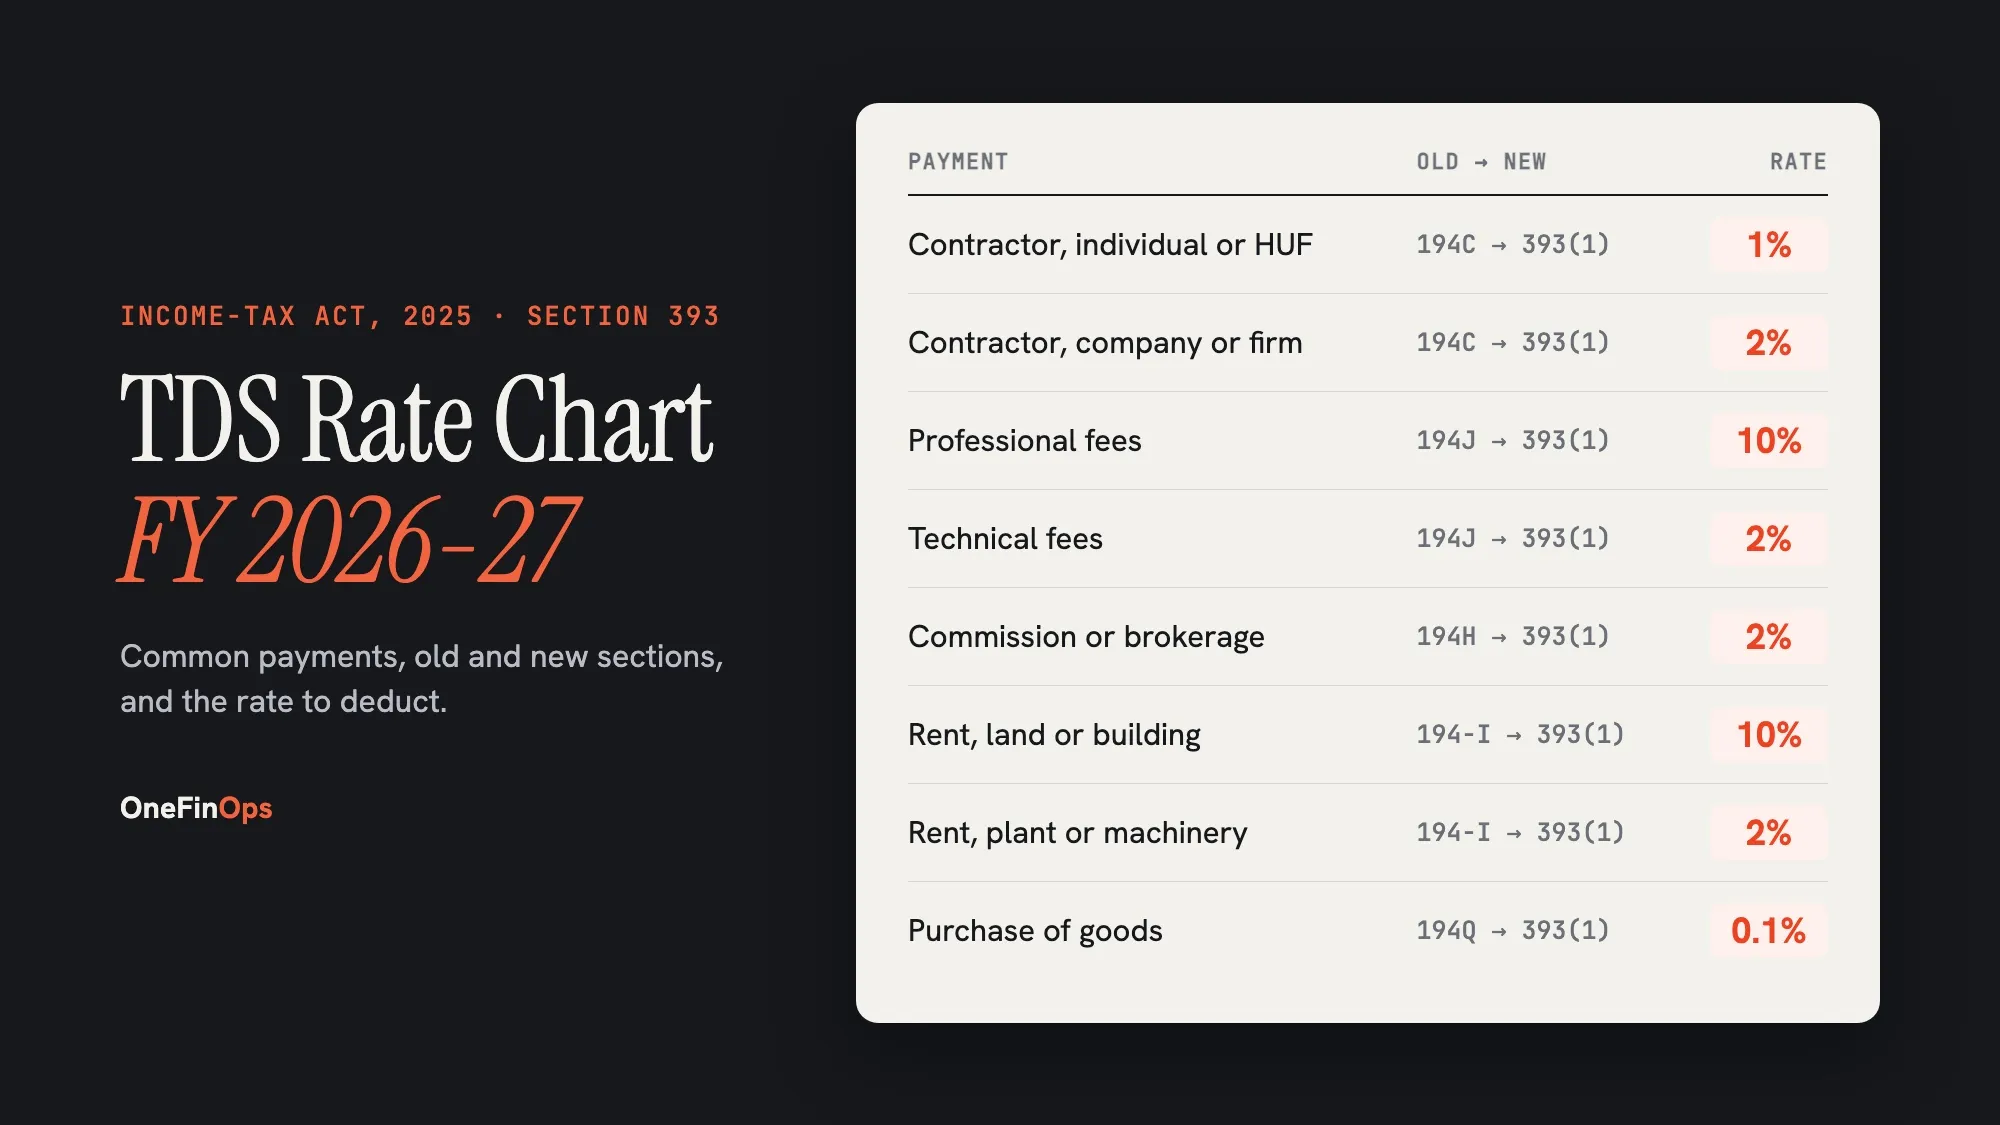
Section 393 has tables instead of one section per payment. Each row names the payment, the payer, the rate and the threshold. Salary TDS is section 392. To find a row by old section or payment code and calculate the TDS, use the TDS rate chart tool.
Section 393(1) table: TDS on payments to residents
Rates and thresholds are for tax year 2026-27. Payment codes are used on the challan and in Form 140 (earlier Form 26Q).
| Old section | Section 393(1) Table Sl. No. | Nature of payment | Rate | Threshold | Payment code |
|---|---|---|---|---|---|
| 194D | 1(i) | Insurance commission | Rates in force (2% for non-company payees, 10% for domestic companies) | ₹20,000 | 1005 |
| 194H | 1(ii) | Commission or brokerage | 2% | ₹20,000 | 1006 |
| 194-IB | 2(i) | Rent paid by individual or HUF not covered as specified person | 2% | ₹50,000 for a month or part of a month | Form 141 |
| 194-I(a) | 2(ii) | Rent for plant, machinery or equipment | 2% | ₹50,000 for a month or part of a month | 1008 |
| 194-I(b) | 2(ii) | Rent for land, building, furniture or fittings | 10% | ₹50,000 for a month or part of a month | 1009 |
| 194-IA | 3(i) | Purchase of immovable property (not agricultural land) | 1% of consideration or stamp duty value, whichever is higher | ₹50 lakh | Form 141 |
| 194-IC | 3(ii) | Cash consideration under a joint development agreement | 10% | Nil | 1011 |
| 194LA | 3(iii) | Compensation on compulsory acquisition of immovable property | 10% | ₹5,00,000 | 1012 |
| 194K | 4(i) | Income from mutual fund units | 10% | ₹10,000 | 1013 |
| 193 | 5(i) | Interest on securities | Rates in force (10%) | ₹10,000 | 1019 |
| 194A | 5(ii) | Interest by a bank, co-operative bank or post office | Rates in force (10%) | ₹1,00,000 for senior citizens, ₹50,000 for others | 1020, 1021 |
| 194A | 5(iii) | Other interest by a specified person | Rates in force (10%) | ₹10,000 | 1022 |
| 194C | 6(i) | Payment to a contractor for carrying out any work | 1% if contractor is an individual or HUF, 2% otherwise | ₹30,000 single sum or ₹1,00,000 aggregate in the year | 1023, 1024 |
| 194M | 6(ii) | Contract work, professional fees or commission paid by individuals or HUFs not otherwise required to deduct | 2% | ₹50 lakh | Form 141 |
| 194J | 6(iii) | Fees for technical services, film royalty, call centre | 2% | ₹50,000 | 1026 |
| 194J | 6(iii) | Professional fees, other royalty, non-compete fees | 10% | ₹50,000 | 1027 |
| 194J | 6(iii) | Director fees or commission (not salary) | 10% | Nil | 1028 |
| 194 | 7 | Dividend by a domestic company | 10% | Nil (no TDS on up to ₹10,000 paid to an individual other than in cash, under 393(4)) | 1029 |
| 194DA | 8(i) | Life insurance policy payout | 2% on the income part | ₹1,00,000 | 1030 |
| 194Q | 8(ii) | Purchase of goods by a buyer with turnover above ₹10 crore | 0.1% | On the amount above ₹50 lakh | 1031 |
| 194P | 8(iii) | Specified senior citizen (75 or older) via specified bank | Rates in force | As applicable | 1032 |
| 194R | 8(iv) | Benefit or perquisite of a business or profession | 10% | ₹20,000 | 1033, 1034 |
| 194-O | 8(v) | E-commerce operator paying an e-commerce participant | 0.1% | Nil (see 393(4) Sl. No. 11) | 1035 |
| 194S | 8(vi) | Transfer of a virtual digital asset | 1% | ₹50,000 or ₹10,000 depending on payer (393(4) Sl. No. 12) | 1037, 1038 |
Commission, rent, interest and professional fees apply to a specified person under section 402: not an individual or HUF, unless above ₹1 crore business turnover or ₹50 lakh professional receipts last year.
Example: an audit firm’s ₹2,50,000 bill in May 2026 falls under Sl. 6(iii), code 1027, at 10%. TDS of ₹25,000 is due by 7 June 2026 and reported in Form 140 by 31 July 2026.
Section 393(2) and 393(3): non-residents and any person
For non-residents, 393(2) Sl. No. 17 covers any sum chargeable to tax, at the rates in force or a lower treaty rate, reported in Form 144. Section 393(3) covers winnings (30%), cash withdrawals under old 194N (2%) and payments to a partner under old 194T (10% above ₹20,000).
How OneFinOps handles section 393
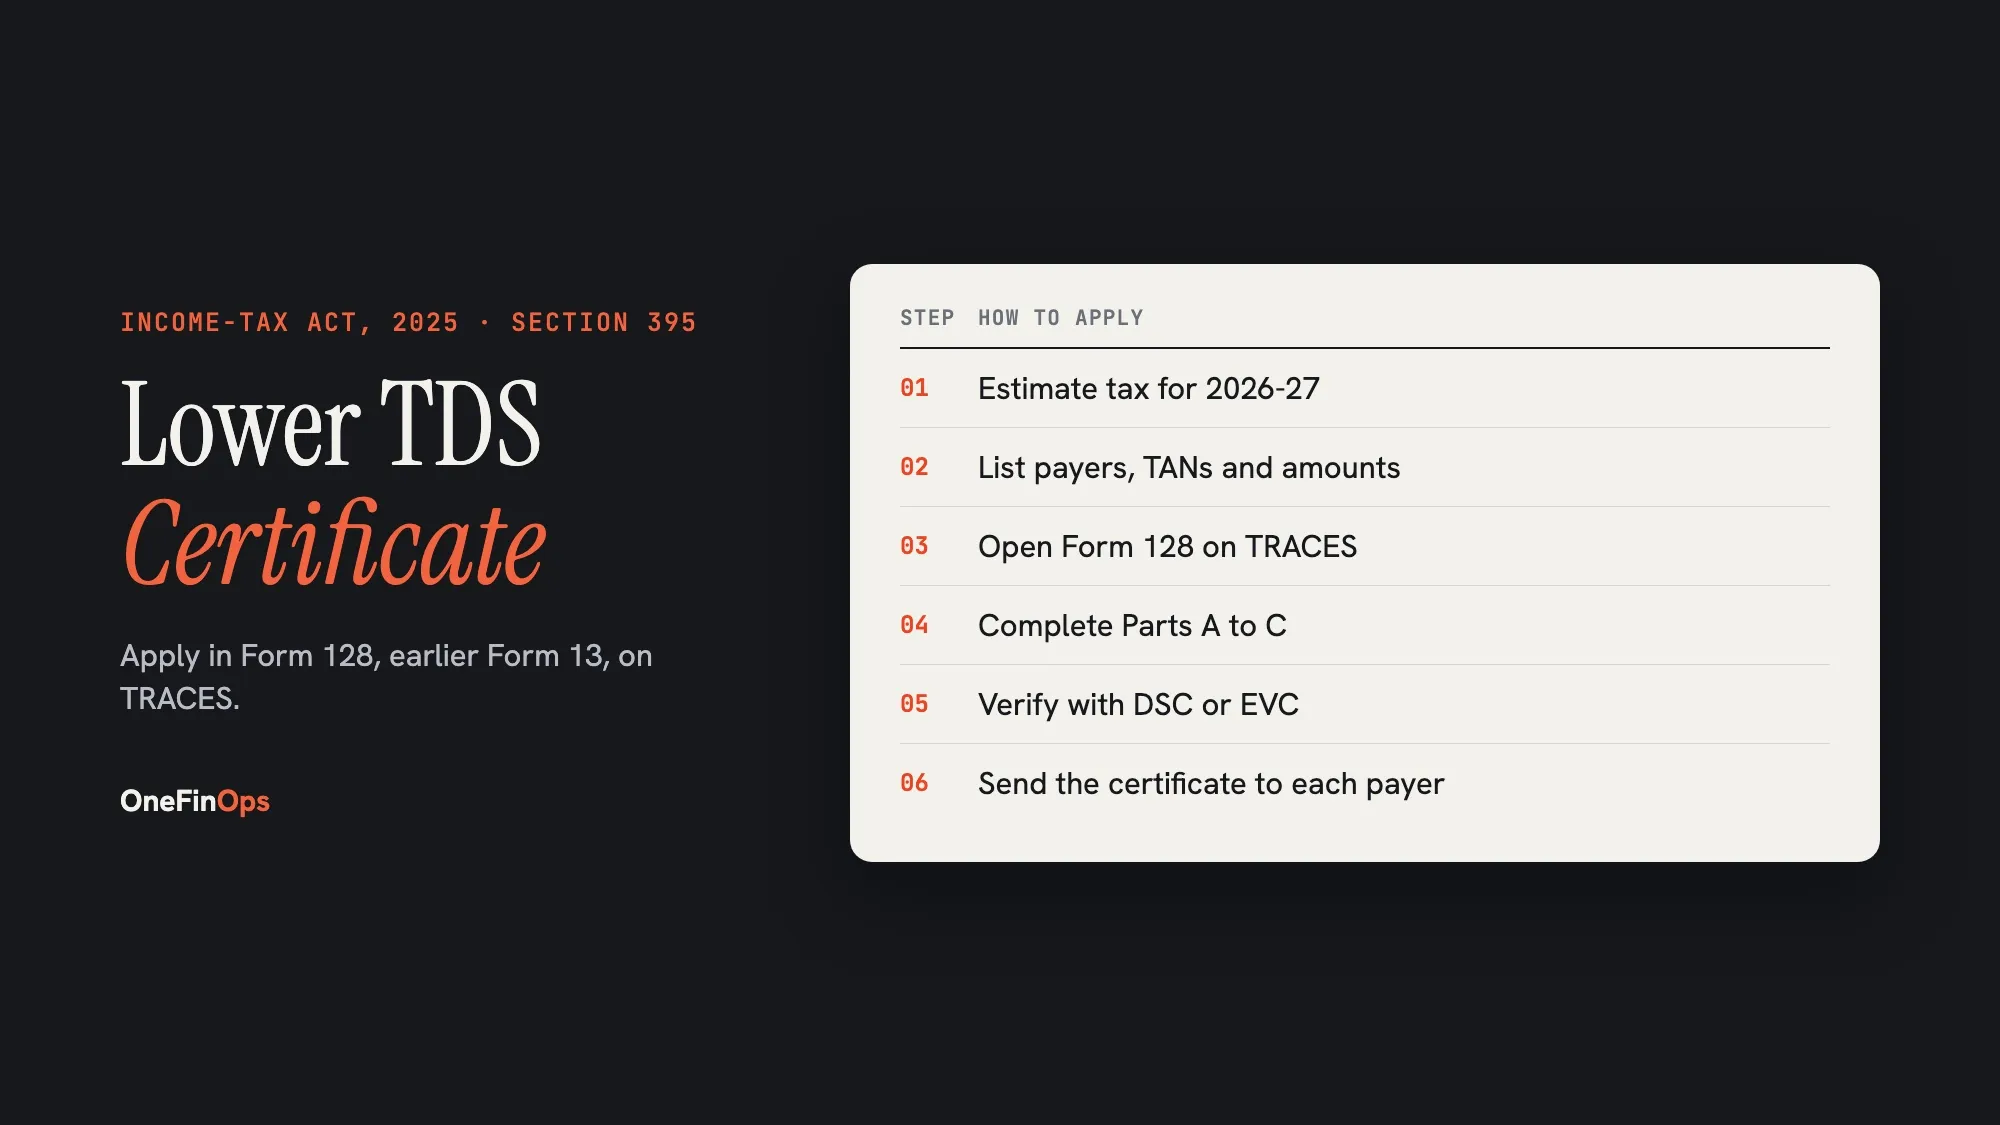
The Payables Agent codes every bill to its tax treatment from the vendor’s status, applies lower deduction certificates and schedules the remittance. The Tax Agent prepares the quarterly return from the same postings and reconciles it to the ledger. The return goes to the named preparer and reviewer before it is filed.
With a separate TDS tool, the row on the bill and the row reported drift apart. In OneFinOps they are one record.