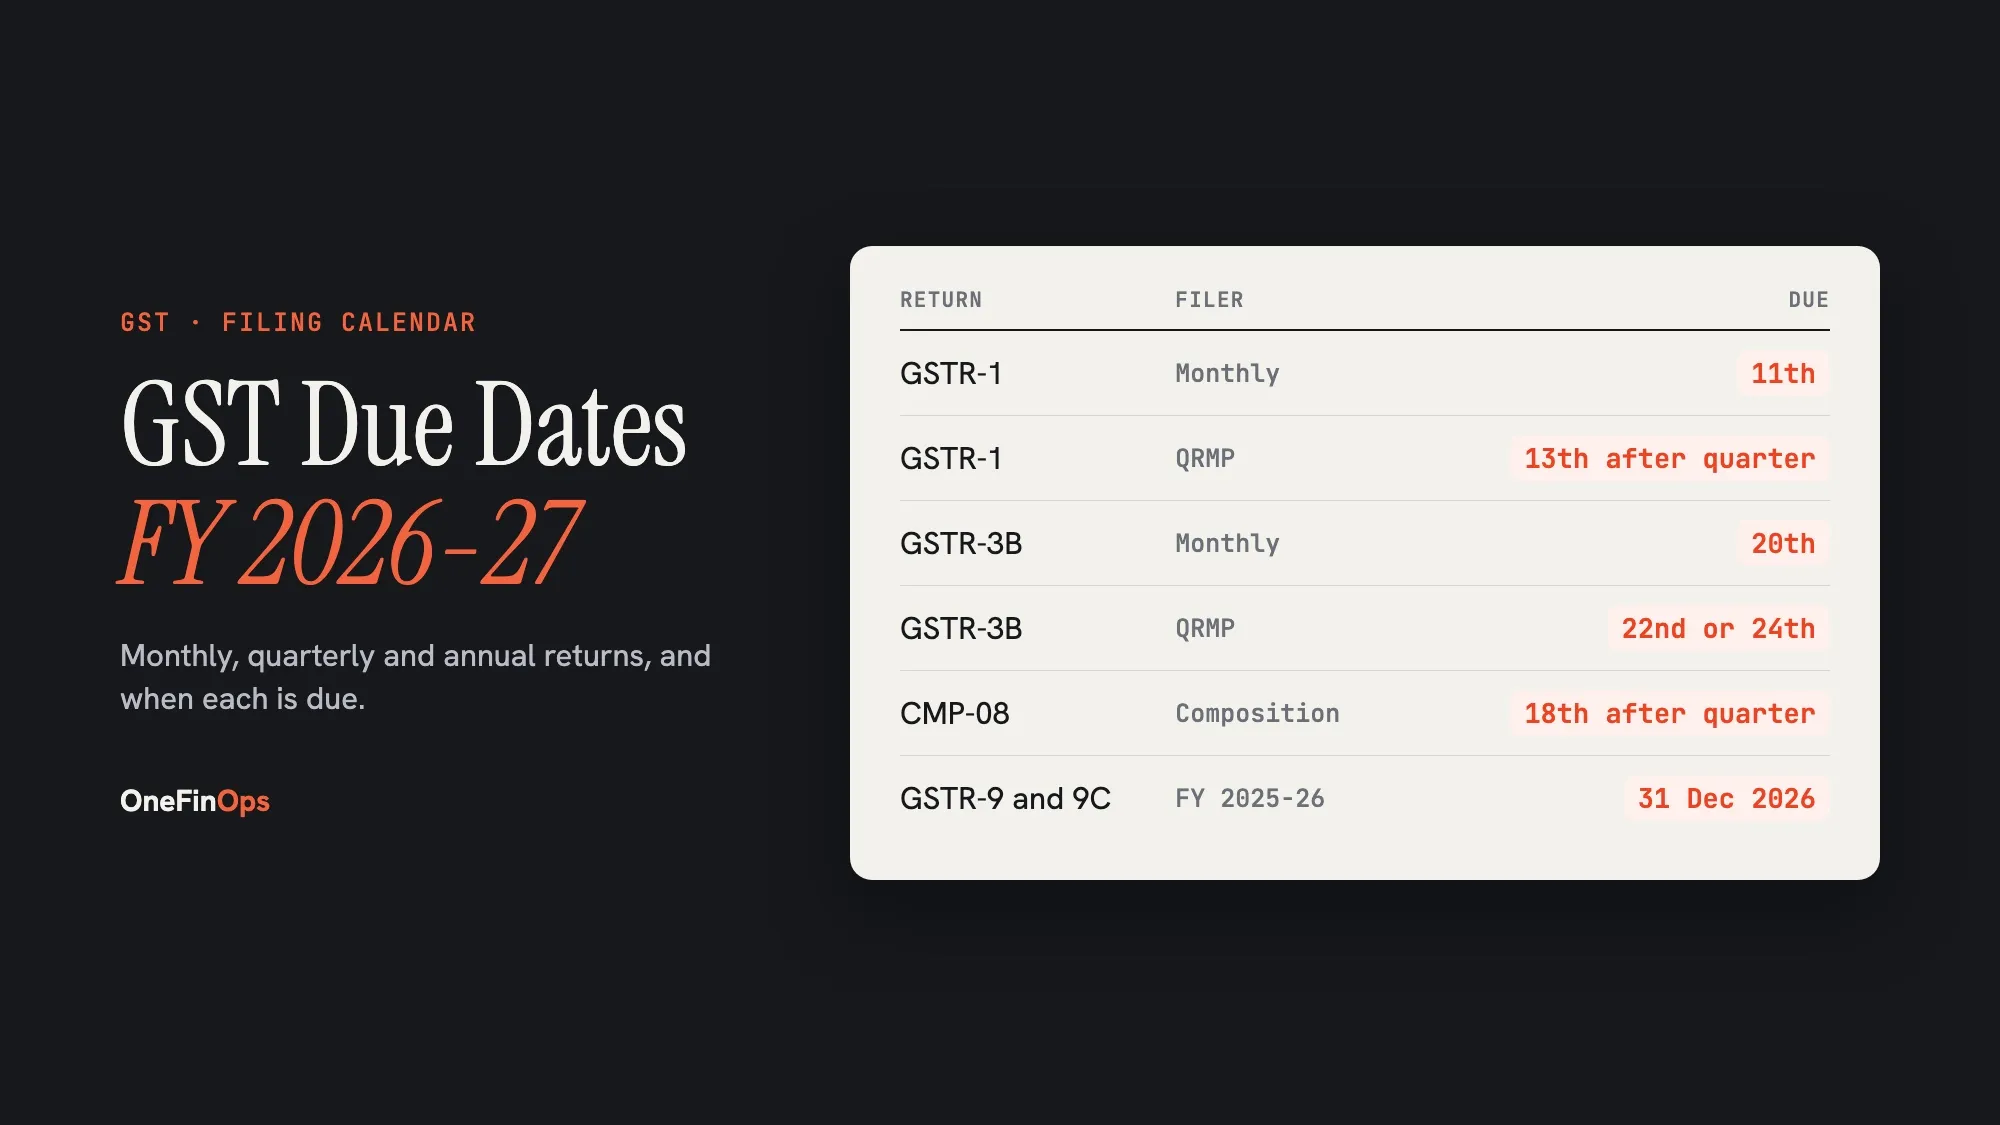
GSTR-9 is the annual GST return summarising a regular taxpayer’s outward supplies, ITC and tax paid for a year; GSTR-9C is the self-certified statement reconciling it with the audited accounts. For FY 2025-26 both are due by 31 December 2026. GSTR-9 cannot be revised, and filing it early closes your window for unclaimed FY 2025-26 credit.
The Tax Agent in OneFinOps reconciles each month’s return to the ledger as it goes, so December starts from twelve reconciled periods.
Key takeaways
- GSTR-9 is mandatory above ₹2 crore turnover; GSTR-9C above ₹5 crore.
- Late fee is ₹50, ₹100 or ₹200 a day by turnover, capped.
- The annual return cannot be filed three years after its due date.
GSTR-9 and GSTR-9C applicability and turnover limit
GSTR-9 applies to normal taxpayers. Composition taxpayers file GSTR-4 instead; Input Service Distributors, non-resident and casual taxable persons, TDS and TCS deductors and OIDAR suppliers do not file it.
| Aggregate turnover in the year | GSTR-9 | GSTR-9C |
|---|---|---|
| Up to ₹2 crore | Optional | Not required |
| Above ₹2 crore and up to ₹5 crore | Mandatory | Not required |
| Above ₹5 crore | Mandatory | Mandatory, self-certified |
Aggregate turnover under section 2(6) is counted at PAN level. A company with ₹3.2 crore in Karnataka and ₹2.4 crore in Tamil Nadu has ₹5.6 crore, so each GSTIN files both forms.
GSTR-9 due date for FY 2025-26
Rule 80 sets the due date as 31 December after the year ends: 31 December 2026 for FY 2025-26. Section 44(2) bars filing more than three years after that, so 31 December 2029 is the last possible date.
Under section 16(4), FY 2025-26 credit can be claimed until 30 November 2026 or the date you file GSTR-9, whichever is earlier. File in October and unclaimed credit is lost from that day. The full calendar is in GST due dates FY 2026-27.
GSTR-9 and GSTR-9C late fees
Under section 47(2), at Notification 07/2023-Central Tax rates (CGST plus SGST), the fee is ₹50 a day up to ₹5 crore turnover and ₹100 a day up to ₹20 crore, each capped at 0.04% of turnover in the State or UT; above ₹20 crore it is ₹200 a day, capped at 0.5%. CBIC Circular 246/03/2025-GST says the return is complete only when both forms, where required, are filed, so the fee runs to the date of the later form.
Example. A company with ₹12 crore turnover files GSTR-9C 75 days late. Late fee is ₹100 × 75 = ₹7,500, under the ₹48,000 cap. It is paid in cash, not from ITC. The GST late fee calculator works out the fee and cap for GSTR-9 and GSTR-9C.
How OneFinOps handles the annual return
The Tax Agent prepares each period’s return from the postings for that registration, reconciles it to the ledger, and stores every difference with its cause beside the filing. It tracks the annual return on the filing calendar with the preparer and reviewer named on it.
It does not file on its own judgement. Every filing goes to those two people before submission. Where monthly returns live in one tool and the books in another, GSTR-9 becomes a December project; with one record, the filed and booked figures are the same number.